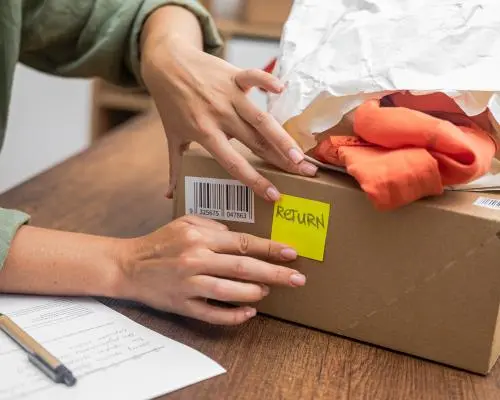
The Return Reserve: A Simple Yet Powerful Tool
For over thirty years, I spent my days crunching numbers and preparing financial statements, yet the most valuable lessons came from unexpected sources. One of those sources was Jerry Crawford, a former carpet wholesaler who ran a modest shop in southern New Jersey. Though he passed away a decade ago, his insights into product returns and inventory management continue to shape how businesses handle risk today.
Latest news
 No Military Fix for US‑Iran Tension, Says Tehran’s Foreign Minister
 Stock Futures Hold Steady as Investors Await Fed Minutes and Higher Yields
 Scientists Identify Brain Region That May Drive High Blood Pressure and Offer New Treatment Pathway
 Macron's Busy Schedule Threatens His Attendance at COP31 and Undermines Paris Agreement Support
Jerry operated a small warehouse and employed roughly fifty people. Despite the size of his operation, he was known for his meticulous approach to customer service and his willingness to share knowledge with anyone willing to listen. During a casual conversation over coffee, he explained how he built a reserve fund to offset the costs of product returns—a practice that many larger firms overlook.
When customers return carpets, the costs don’t end with the refund. There are shipping fees, restocking expenses, and the loss of potential profit. Jerry’s method involved setting aside a percentage of each sale to cover these eventualities. He would calculate the average return rate for his inventory and create a reserve that matched that figure. By doing so, he ensured that a sudden spike in returns would not cripple his cash flow.
Why Most Companies Ignore the Practice
According to Jerry, the reserve worked like a safety net. „You’re not just protecting the bottom line,” he said, „you’re also protecting the people who work for you. If a shipment comes back, you can pay your staff without scrambling for funds.” This approach helped maintain stability during seasonal dips and unexpected market shifts.
Many businesses assume that returns are infrequent enough to ignore or that they can absorb the cost through general operating funds. However, the reality is that return rates can fluctuate dramatically, especially in industries where product quality varies or customer expectations change. Without a dedicated reserve, a company may face liquidity crises, missed payroll, or forced asset sales.
The lesson from Jerry’s experience is that a proactive reserve is not a luxury; it is a necessity for sustainable growth. By embedding this practice into their financial planning, companies can reduce volatility and build trust with suppliers and employees alike.
How to Implement a Return Reserve Today
Creating a return reserve is straightforward. First, analyze historical return data to determine an average rate. Next, decide on a reserve percentage that covers the expected cost per return, including shipping and restocking. Finally, set up a separate account or earmarked line of credit to hold the funds. Regular reviews will adjust the reserve as return patterns evolve.
Adopting this strategy can improve cash flow, strengthen employee relations, and enhance customer satisfaction. It also signals to investors that the company is managing risk responsibly.
Frequently Asked Questions
What percentage should I set aside for returns? Start with the average return rate for your industry and add a buffer—typically 5–10% of that rate—to cover unexpected spikes.
Can this reserve be used for other purposes? No. The reserve should be kept separate and used only for return-related costs to maintain its integrity.
Does this apply to all product types? It is most effective for high‑volume, high‑return products, but any business with a significant return rate can benefit from a dedicated reserve.